SIP vs lump sum: which investment strategy suits you in 2026?
Neither is better. Pick the one that matches how your money arrives: a SIP for monthly salary, a planned lump sum for bonuses, fees or inheritance.
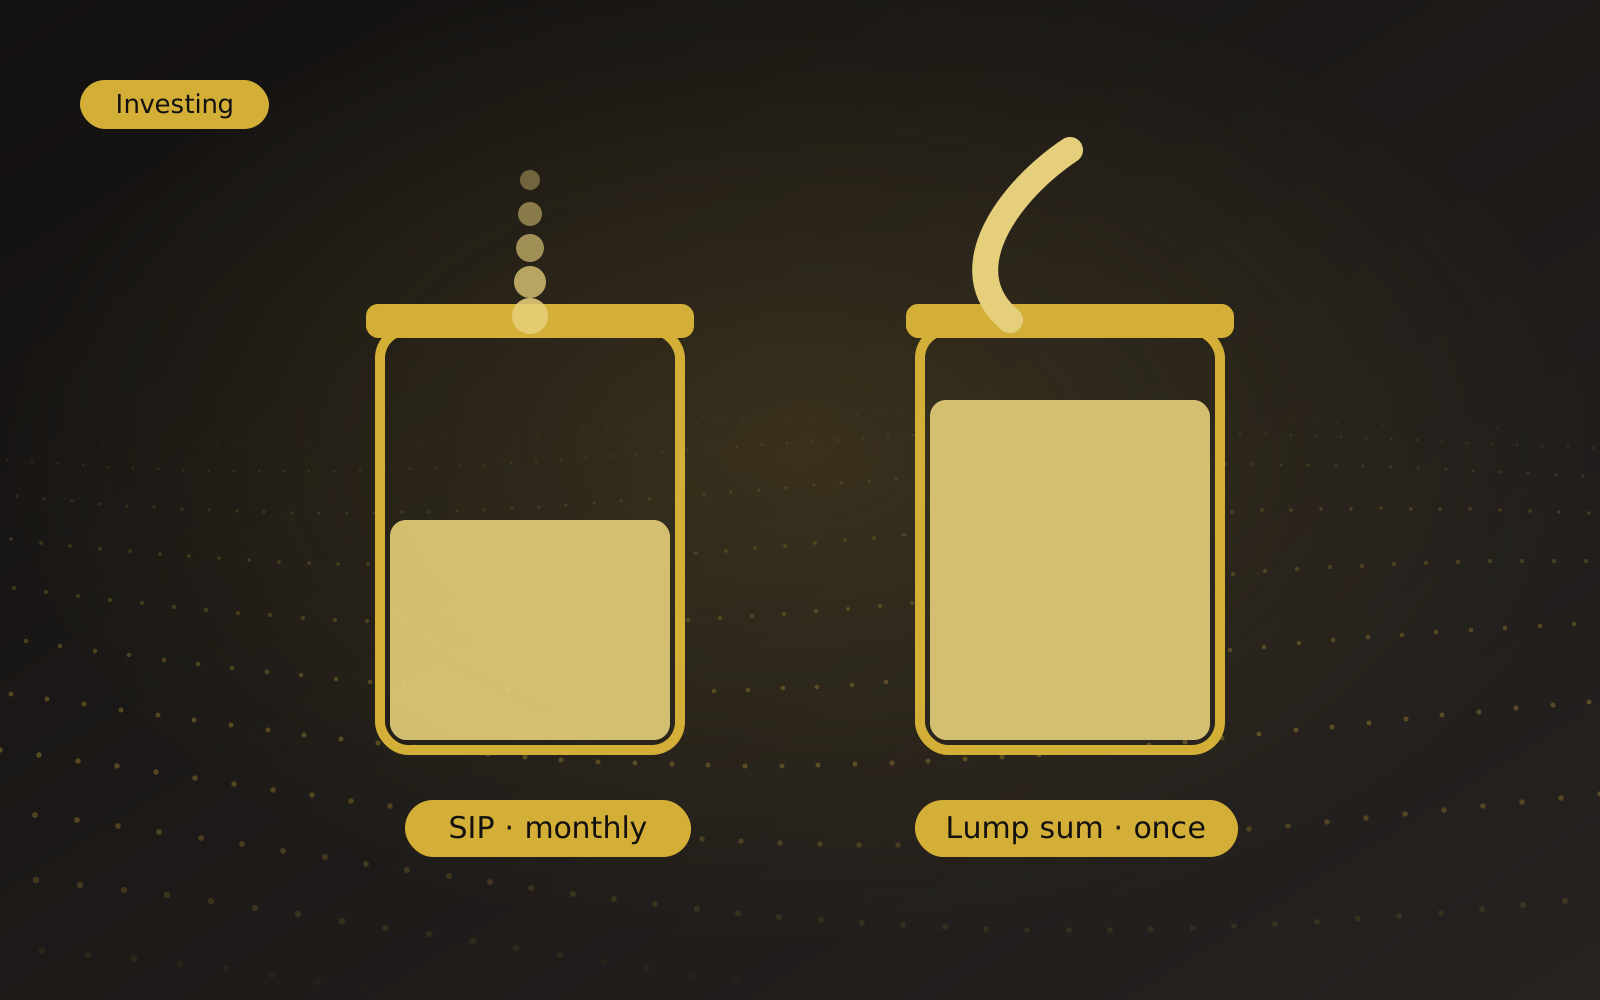
The honest answer is that neither method is better than the other; the right one depends on how your income arrives. A monthly salary suits a SIP, while a bonus, a professional fee or an inheritance is already a lump sum and needs a plan rather than a debate. This guide covers when each fits, what matters more than the choice, and the two mistakes we see most often.
Start with how your money arrives
A SIP (systematic investment plan) puts a fixed amount into a mutual fund on a fixed date every month. A lump sum puts a larger amount in at once. Your money already has a shape, and the method should follow it.
If you earn a salary, your money arrives monthly. Say ₹1.2 lakh lands on the 1st. A SIP on the 5th moves part of it into investments before it becomes spending. There is no lump sum to debate about.
If you are a doctor, consultant, contractor or shop owner, your income is lumpy. Some months bring ₹4 lakh, some bring ₹40,000. A fixed monthly SIP feels like a burden in lean months and far too small in good ones. You need a different rhythm.
If you have just received a bonus, a retirement benefit, sale proceeds or an inheritance, the money is already in your bank. The question is not SIP or lump sum but what to do with it, and how fast.
SIP is really about discipline
The quiet strength of a SIP is not a mathematical edge. It is that the decision is made once and then repeats without you. No monthly willpower, no reading the news. For most salaried families, that automation is the single biggest reason their investments actually build up over a decade.
A SIP also buys units at many prices over the years, which softens the discomfort of investing at a high point. That is a comfort, not a promise; markets can fall for long stretches.
Worth knowing
The right method is the one you will keep running for ten years without thinking about it.
Two habits help. Step up the SIP amount every time your salary rises, even by ₹1,000. And set the SIP date a few days after salary day, so it goes out before the spending does.
Lump sum needs a plan, not a formula
When a large amount arrives, the common advice is "stagger it over six or twelve months". That is a reasonable choice for someone who would lose sleep if the market fell the week after investing. It is a choice, not a rule. If the money is for a goal ten or fifteen years away and your asset mix already has a cushion, investing it sooner is equally defensible. Nobody can tell you in advance which path would have done better.
What we do insist on is a written plan before the money moves anywhere:
- Clear any high-cost loan first, especially credit card dues.
- Top up your emergency fund to six months of expenses if it is short.
- Decide what goal this money serves and how far away that goal is.
- Only then choose the mix of equity and debt, and how quickly to deploy.
For lumpy professional income, keep a floor SIP you can afford even in a poor month, and move a fixed share of every good month's surplus into investments as a lump sum. The habit stays, the amount flexes.
What matters more than SIP vs lump sum
Over fifteen years, the method of entry makes a small difference. Three other things make a large one.
| Factor | Why it matters more |
|---|---|
| The goal | College fees in six years and retirement in twenty need different approaches |
| The horizon | Money needed within three years should not be in equity at all |
| The asset mix | Your split across equity, debt, gold and property matters far more than the entry date |
Once a family writes down the goal behind each investment, the SIP versus lump sum question usually answers itself.
The two mistakes to avoid
The first is stopping SIPs when markets fall. A fall is uncomfortable, but a SIP that pauses in a downturn skips the very months it was designed for. If cash is tight, reduce the amount; do not stop it.
The second is waiting for the "right time" with a lump sum. We meet people who have held ₹20 lakh in a savings account for two years waiting for a correction. Inflation does not wait. If you cannot bring yourself to invest it all, stagger it on a fixed schedule and stop watching the index.
Both mistakes come from trying to time the market instead of running a plan. Mutual fund investments carry market risk, and no method removes that risk. A plan simply makes sure the risk you take matches the goal you have.
What to do this week
- Write down every goal you are investing for, with a year next to each one.
- Check your SIP date and move it to within five days of salary day.
- If any lump sum is sitting idle, list what it is for and when you need it.
If you would like a second pair of eyes on your plan, book a free 30-minute review with one of our directors.
This article is for information only and is not investment, tax or legal advice. Figures are illustrative. Mutual fund investments are subject to market risks; read all scheme-related documents carefully before investing. Bhavya Sampada is an AMFI-registered Mutual Fund Distributor, ARN 266666.