Articles and videos
Money guidance you can act on
Plain guides to the questions families ask us most, and case studies of how we helped clients with theirs. Written by the people who run your review.
Latest articles
Planning your child's education fund without derailing your retirement
Put a date and a rupee figure on the course, start early, keep the money separate from retirement, and shift to safer options as the date nears. Education can be borrowed for; retirement cannot.
After a loss: a term claim settled, and a plan that gave Lakshmi time
When Lakshmi lost her husband, we helped file the term claim and EPF paperwork, parked the money safely for six months, and only then built a written plan around her needs.
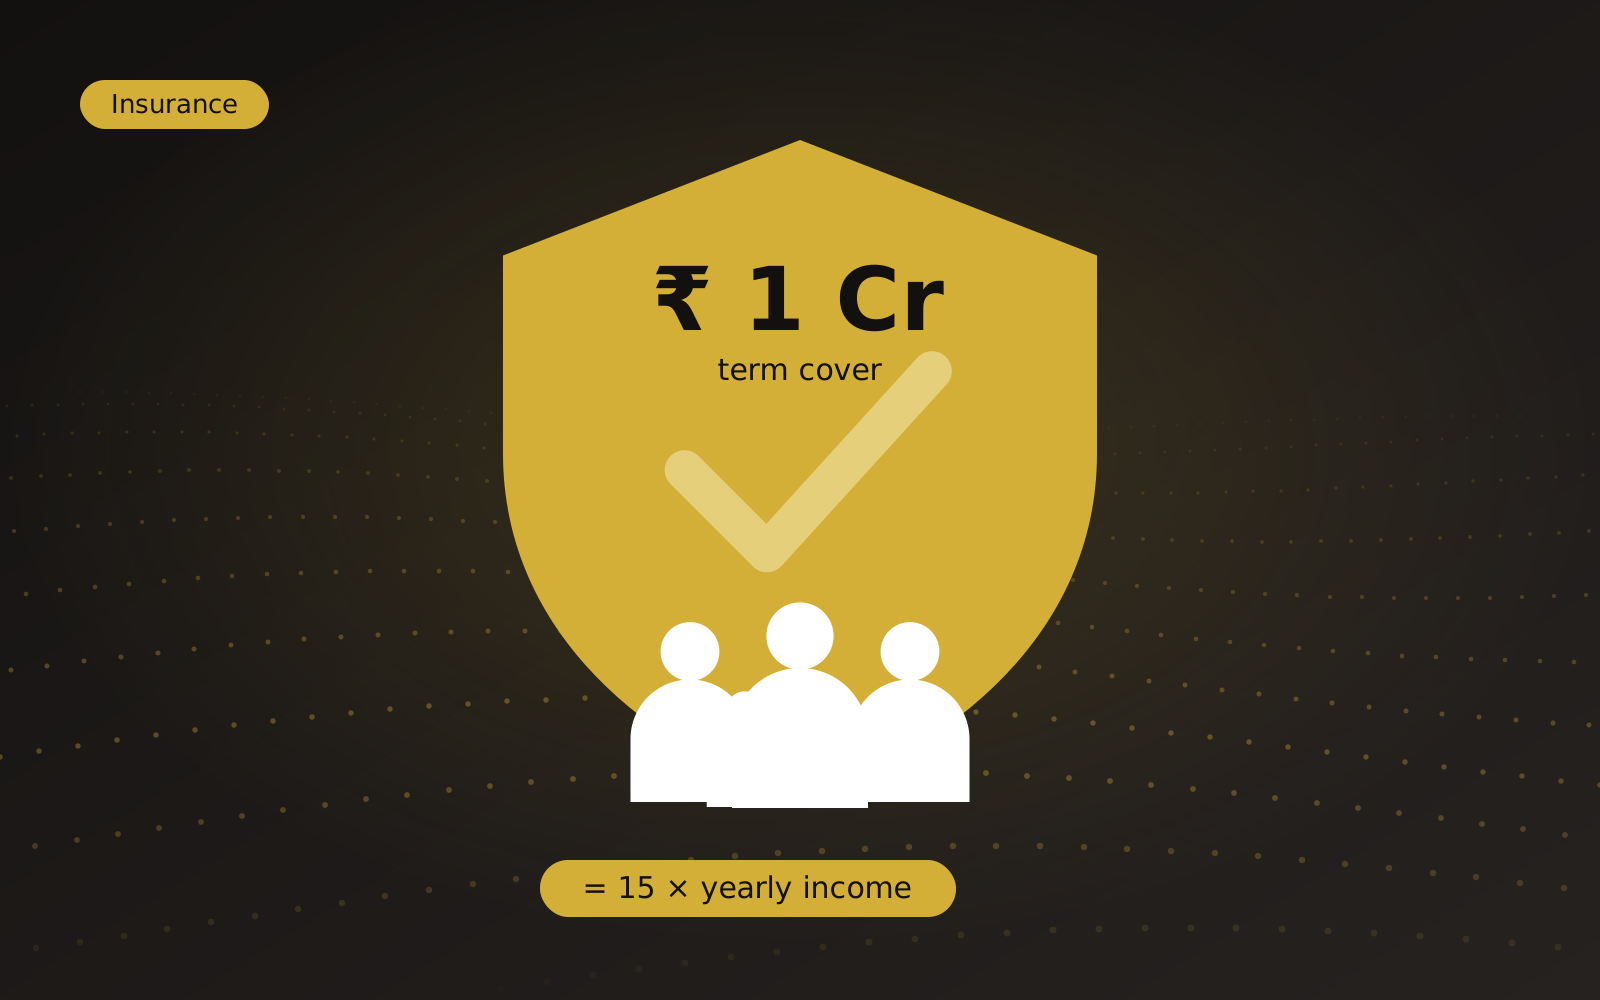
How much term cover does your family actually need?
Add the income your family needs replaced, the loans to clear and the goals to fund, subtract what you already own. That number, not a thumb rule, is your cover.
Coming home from Dubai: a returning family's money, put in order
A family returning from Dubai to Bengaluru had scattered accounts, no Indian health cover and a house to buy. We sequenced it: cover first, then accounts, then the house, with retirement intact.
The 20-year savings policy: what it really gives you, and what to do if you have one
A savings policy mixes a small life cover with an opaque savings plan. Continue, make it paid-up, or surrender, case by case, and never before term cover is in place.
Health cover for parents over 60: what to buy and what to check
Buy parents a separate senior policy, not a slot on your family floater. Check waiting periods, room-rent caps and co-pay before price, and disclose everything.
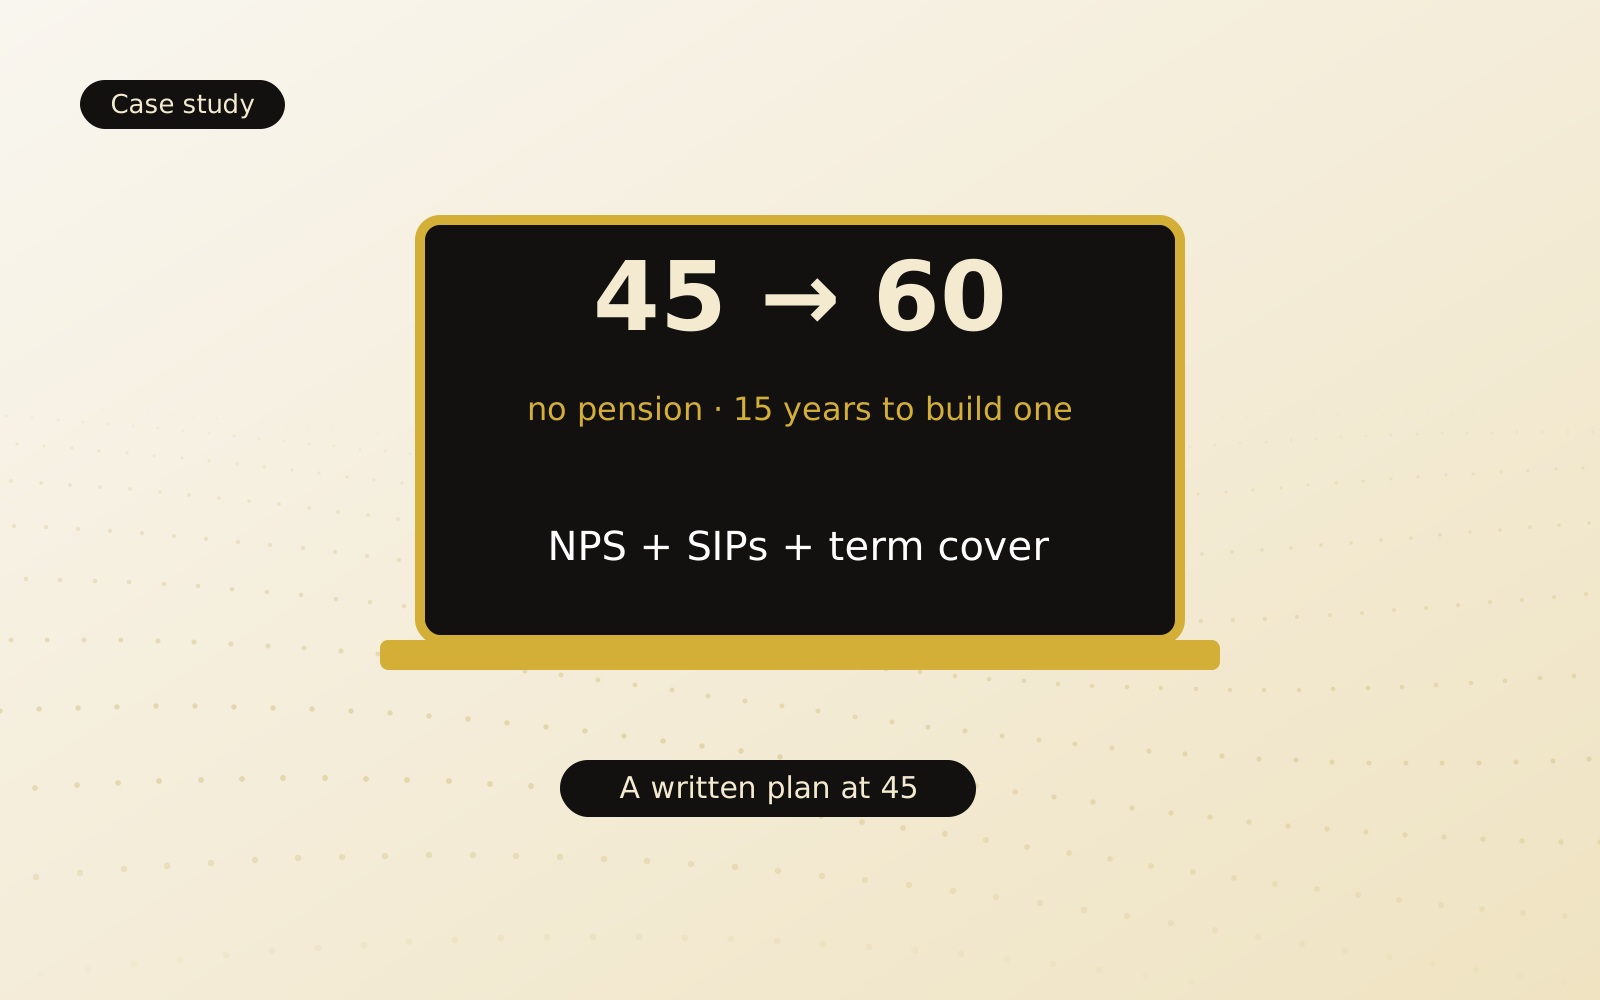
A government teacher's retirement plan, built at 45
An NPS-era teacher with no old pension and no retirement number got one. We mapped his NPS, started goal SIPs, made an endowment policy paid-up and built an emergency fund.
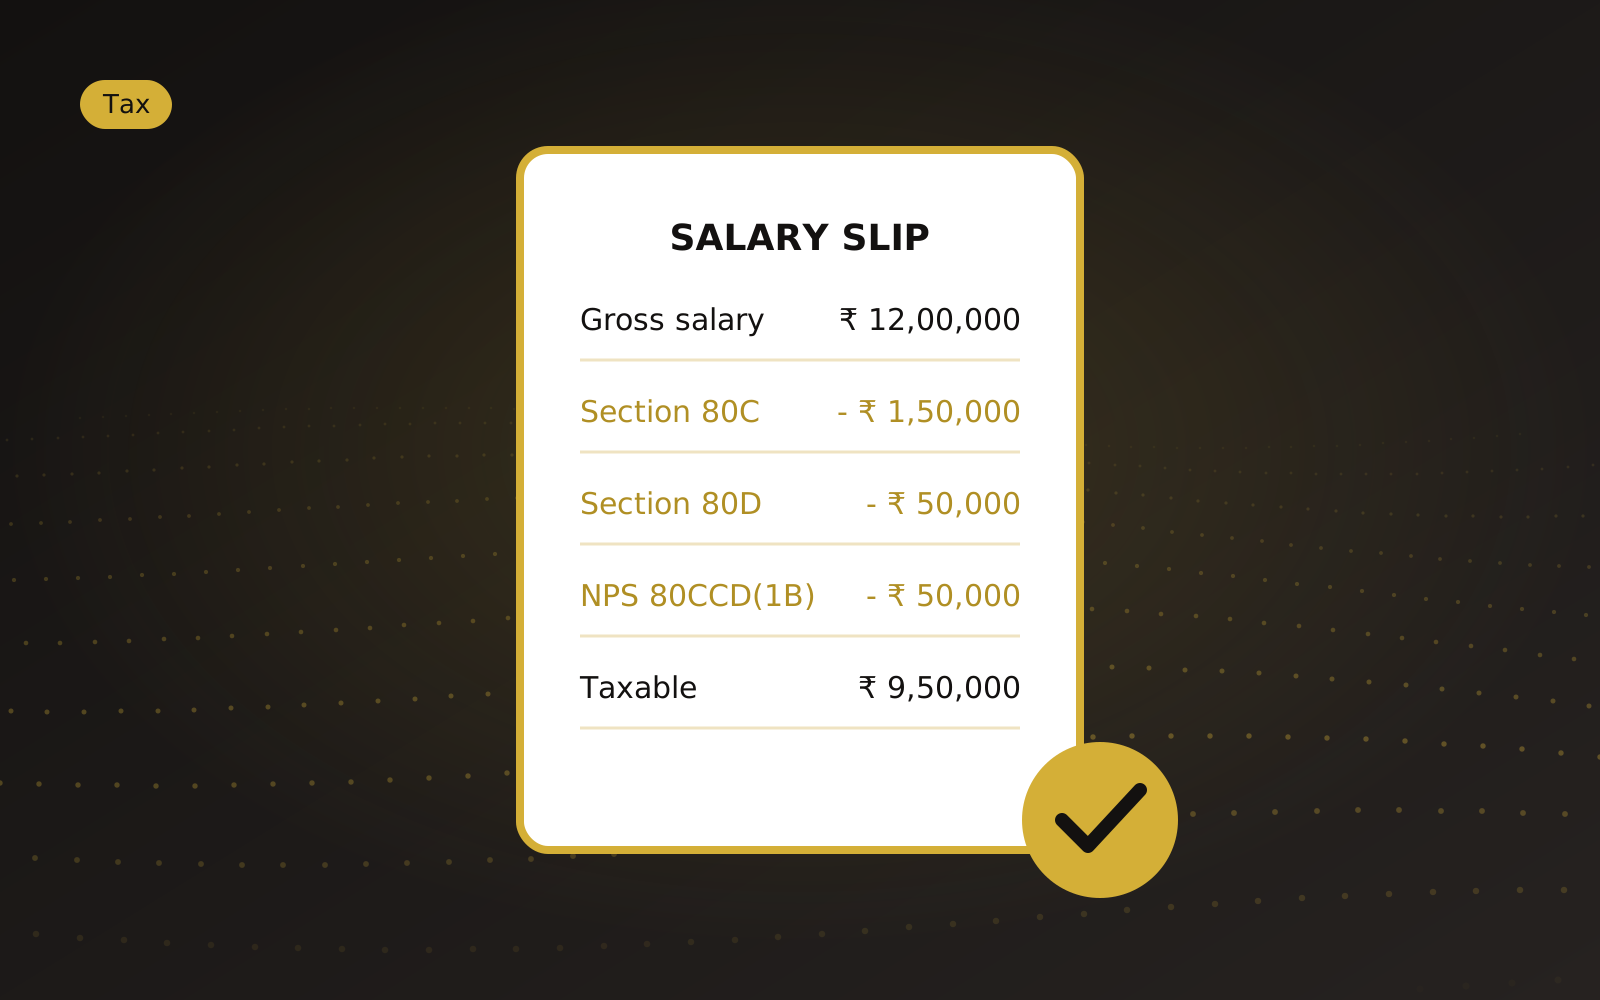
5 legal ways salaried and government employees can reduce tax
First decide old regime or new. Then use 80C, 80D, HRA, home-loan interest and NPS where they apply, and never buy a policy in March just to save tax.
When to stop an SIP, and when not to
Stop an SIP when the goal is near, the fund no longer fits the plan, or income has fallen. Do not stop because markets fell or someone has a tip.
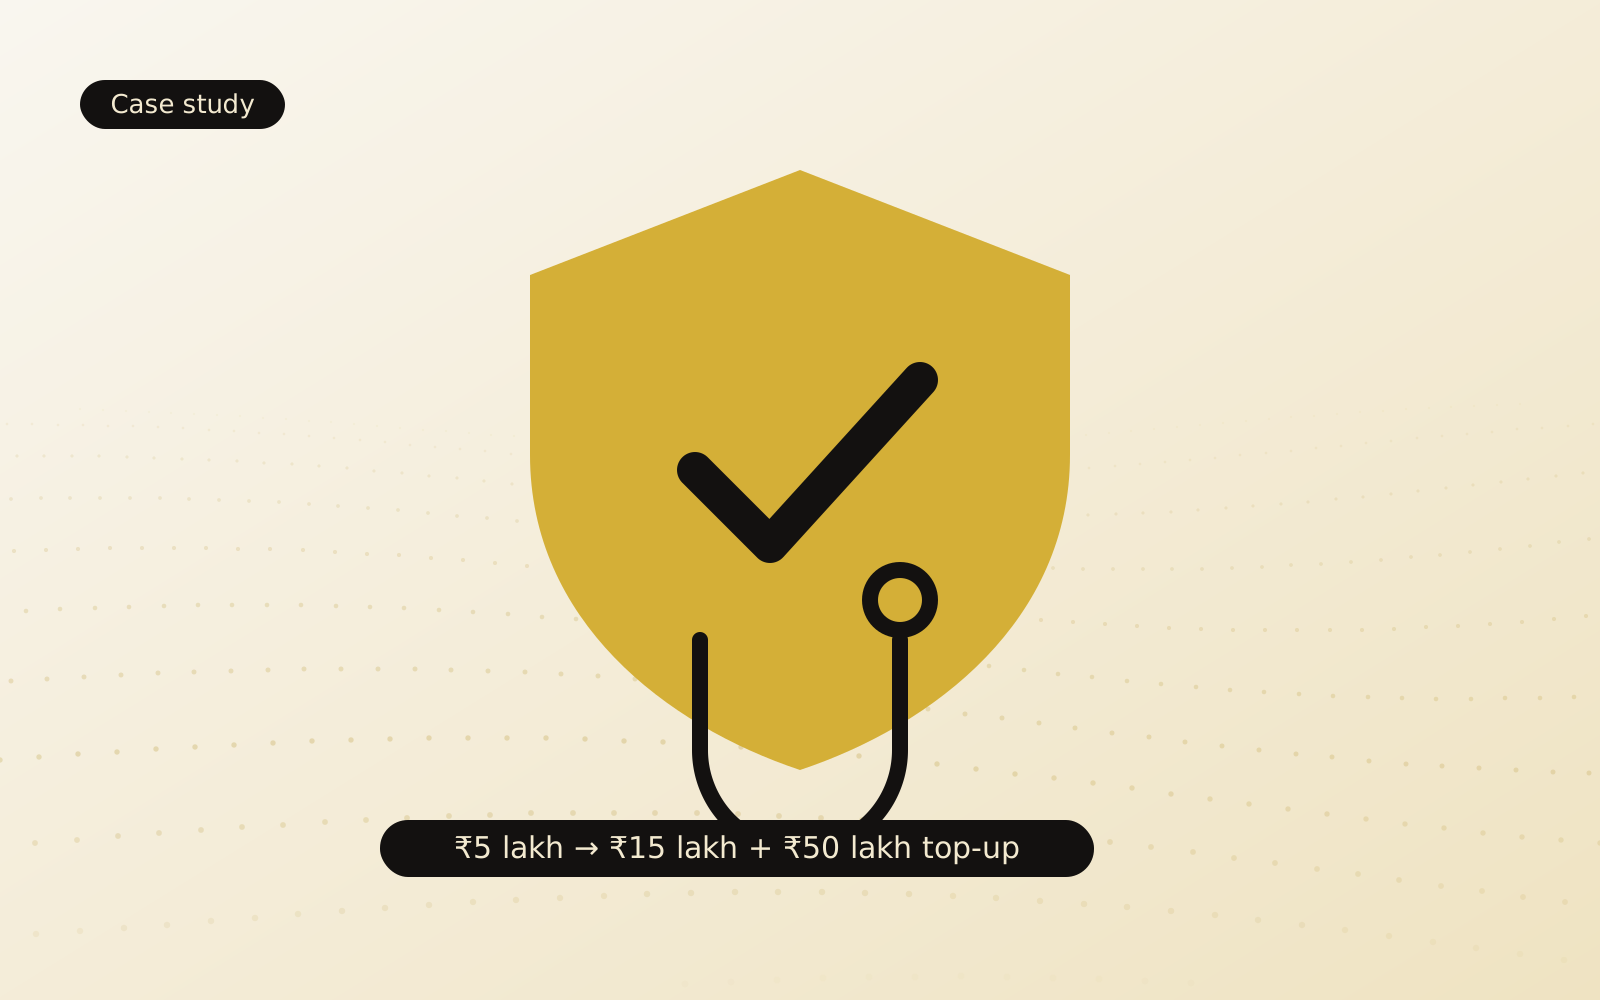
A doctor's health cover, rebuilt before it was needed
A ₹5 lakh floater from 2014 with parents on it was not enough for a family of four in 2026. We separated the parents, raised the base cover and added a super top-up.
How much do you really need to retire comfortably?
Start from today's monthly spend, adjust for what stops and what grows, inflate it to your retirement year, then multiply by about 25. A starting point, not a verdict.
How a Warangal couple cut their EMI without stretching the loan
A balance transfer was not the answer. A rate reset with the same lender, one part-prepayment and a shorter tenure cut the EMI and kept the retirement SIP running.
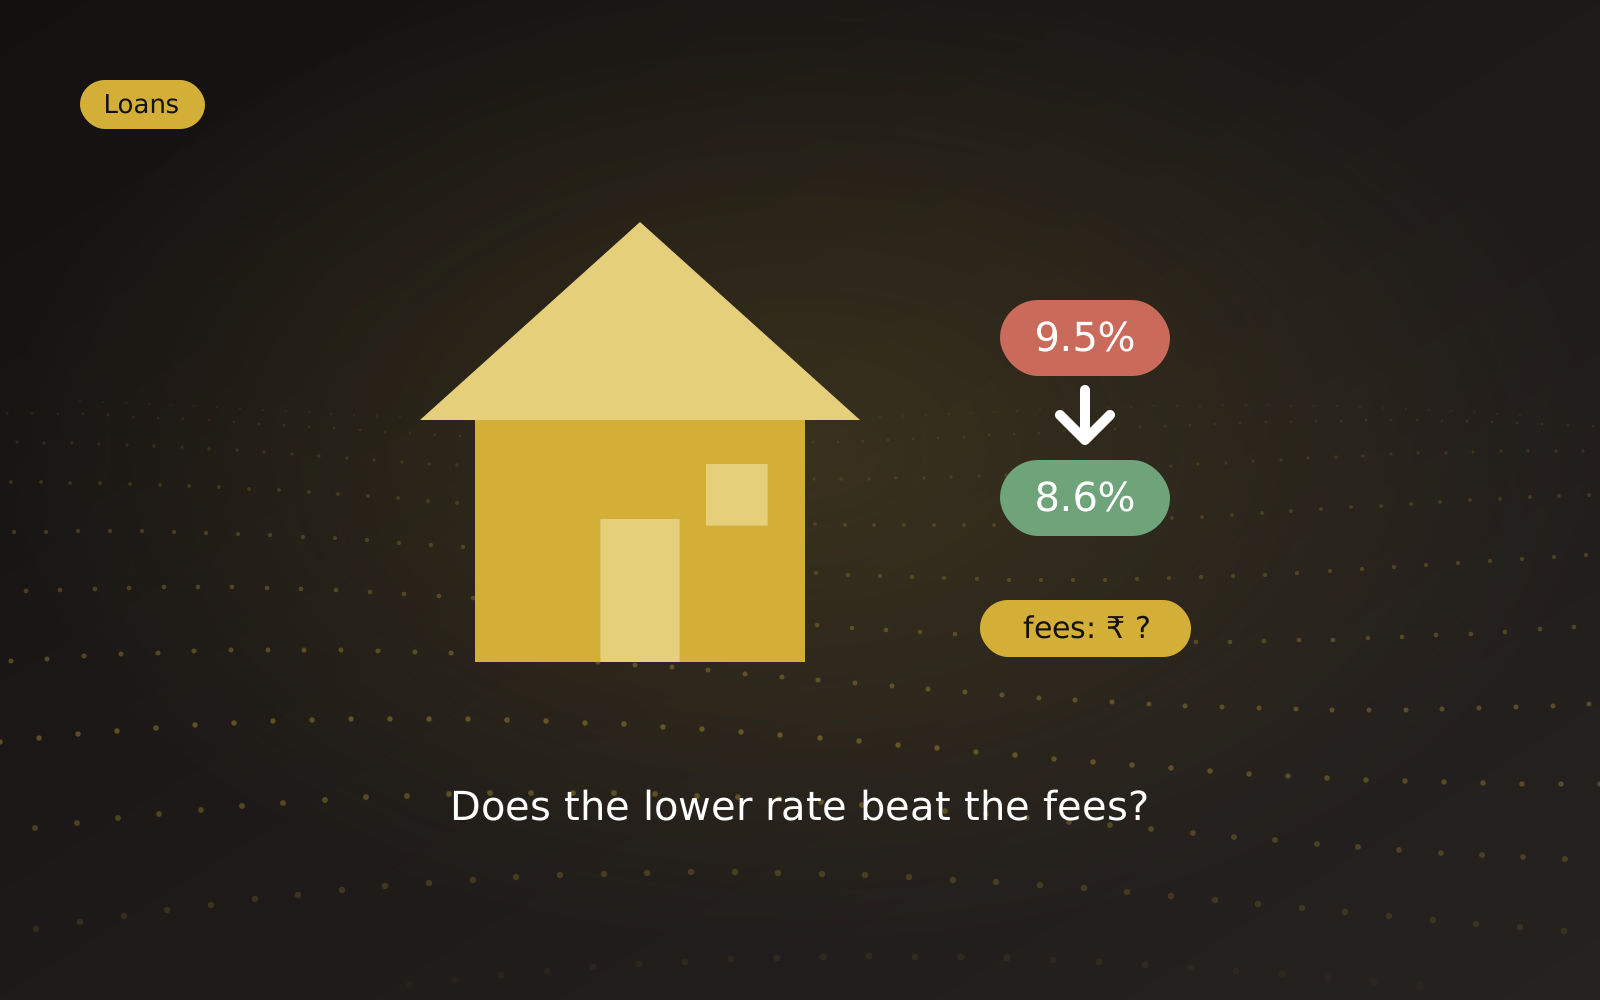
Home loan balance transfer: when it saves money and when it doesn't
A transfer helps when the rate gap is wide, the tenure left is long, and fees are small. Late in a loan it rarely pays. Ask your own lender first.
The emergency fund: how much, where to keep it, and when to touch it
Keep six months of essential expenses, twelve if you are single-income or self-employed, in a savings account and sweep FDs, away from long-term money.
SIP vs lump sum: which investment strategy suits you in 2026?
Neither is better. Pick the one that matches how your money arrives: a SIP for monthly salary, a planned lump sum for bonuses, fees or inheritance.
From our YouTube channel
All videosShort, plain explainers on The Wealth Theory, our channel: one money idea in under a minute. The three newest videos appear here automatically. Refreshed every 24 hours from the channel
 A wealth manager by profession, but so much more behind the scenesWatch on YouTube · Short
 How did he calculate that so fast? It’s called the Rule of 72!Watch on YouTube · Short
 You don’t have to be rich to start investingWatch on YouTube · Short
Newsletter
One useful money idea a month
No market noise, no product pushes. Unsubscribe any time.
Reading is a start. A plan is better.
Book a free review with one of our directors and see where you stand.